Money habits get passed down at the kitchen table long before anyone opens a brokerage account. Kids absorb how their parents talk about bills, jobs, and risk, and those lessons tend to stick for life.
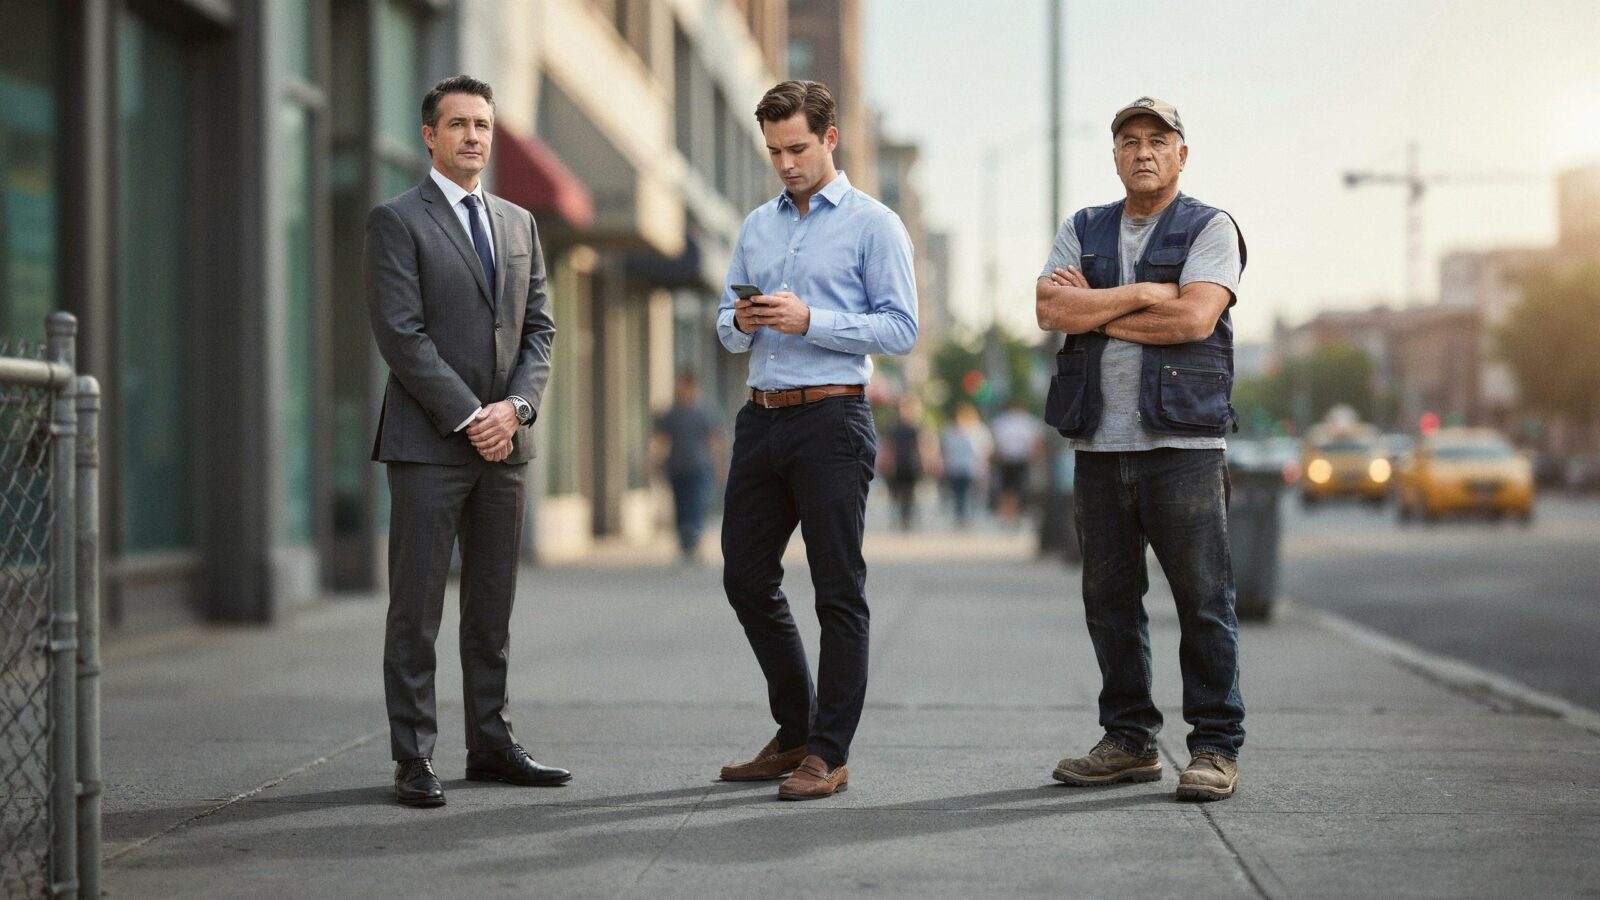
How you earn your income is part of class, and so is a whole set of beliefs about time, work, and what money is supposed to do. The chart below lays out ten of the biggest differences side by side, and the sections after it walk through each one.
| Category | Upper-Class Mindset | Middle-Class Mindset | Working-Class Mindset |
|---|---|---|---|
| Primary Focus | Generational wealth and legacy | Career security and stability | Daily and monthly survival |
| View of Money | A tool for growth and buying back time | A reward for labor | A scarce resource for necessities |
| Relationship with Time | Planning across decades | Life stages and milestones | The current pay cycle |
| Risk and Failure | Calculated risk with failure as tuition | Avoids risk to protect lifestyle and credit | Risk as a danger to basic needs |
| Perception of Work | Ownership, delegation, and systems | Expertise traded for salary | Hourly labor for a paycheck |
| Networks | Deal flow, board seats, and access | Coworkers, neighbors, and alumni | Family and close friends |
| Education | Elite networks and leadership | Credentials for stable jobs | A trade skill or a costly gamble |
| Financial Strategy | Private equity, real estate, and tax planning | 401(k)s, index funds, and mortgage payoff | Cash flow, side gigs, and short-term credit |
| Consumption | Discreet luxury and time savings | Recognizable brands and upgrades | Durability and affordability |
| Problem-Solving | Hiring experts and deploying capital | Personal effort and formal rules | Do-it-yourself skills and community help |
1. Primary Focus
Wealthy families think in generations. The goal is a base of assets, connections, and influence that outlives the person who built it.
The middle class aims for stability through a steady job, home equity, and a retirement account that grows every year. Working-class households have a shorter horizon because rent, groceries, and the electric bill come due before anything else gets a turn.
2. How Each Class Views Money
To the upper class, money works like an employee. It gets sent out to buy assets that appreciate, pay income, and free up hours.
Middle-class earners see money as payment for work already done, so it goes into savings accounts or toward keeping up a certain standard of living. For working-class families, money is scarce. It covers the necessities and any emergencies that happened this week.
3. Relationship with Time
A wealthy investor might judge a decision by where it leaves the family decades from now. That long view changes which deals look smart and which look silly.
The middle class runs on milestones like graduation, promotion, the first house, and retirement, which comes around 65. Working-class time shrinks down to the pay cycle. Planning ten years out is hard when Friday’s check already has a job to do.
4. Risk and Failure
Upper-class families take risks on purpose. A failed venture counts as tuition, and capital reserves, along with legal structures like LLCs, keep the damage away from personal wealth.
Middle-class people usually avoid risk because one bad bet could wreck their credit or their lifestyle. In working-class homes, risk looks like actual danger. A single mistake can cost a car or an apartment.
5. How Work Is Perceived
Owners care about equity and systems. They hand off daily execution and build businesses that keep running while they’re on vacation.
The middle class values degrees, titles, and hard work, and it accepts trading time for a salary as the normal deal. Working-class jobs are often physical or hourly. Pay stops when the clock does.
6. Social and Professional Networks
Rich people build relationships around access. Board seats, deal flow, and shared investments hold these circles together.
Middle-class networks form at the office, in professional associations, and through neighbors and alumni groups. Working-class networks are smaller and far more hands-on. A cousin watches the kids, a buddy helps fix the truck, and the favor is repaid later.
7. Approach to Education
For elite families, school is about who you meet and how you learn to lead. Alumni connections and financial literacy count as much as the diploma.
The middle class treats degrees as the ticket to steady employment and raises. Working-class families view education with greater suspicion. A trade can pay off quickly, while a four-year degree with heavy loans might never recoup its cost.
8. Financial Strategy
Upper-class portfolios lean on private equity, real estate and stocks, with tax planning built into every move. Keeping capital matters as much as growing it.
Middle-class savers rely on 401(k)s and index funds while chipping away at the mortgage and guarding their credit scores. Working-class money management comes down to cash flow. Over time, side gigs and short-term credit fill the gaps between paychecks.
9. View of Consumption
Many wealthy households spend with discretion and put their money toward private services, exclusivity, and anything that saves time. Flashy spending exists at every income level, but people with established wealth often feel less need to prove it.
Middle-class spending tends to lean on recognizable brands, newer cars, and home renovations that signal success to peers. Working-class buyers usually prioritize function and price and try to get the longest possible life out of what they buy, even when a tight budget forces them to choose the cheaper option.
10. Problem-Solving Approach
When the wealthy hit a complicated problem, they hire someone. Lawyers, accountants, and specialists get paid to handle it.
The middle class solves problems through personal effort and by working within the rules of banks, schools, and HR departments. Working-class people fix things themselves. If they don’t have the skill, a neighbor or relative usually has it.
Conclusion
None of these mindsets is locked in place. Plenty of people raised in working-class homes have built serious wealth, and plenty of rich families have lost theirs in a generation or two.
Start by noticing which habits came from your upbringing and asking whether they still make sense. Borrowing the upper class’s long-term horizon costs nothing, and a working-class eye for durability keeps spending in check while your assets grow.
PakarPBN
A Private Blog Network (PBN) is a collection of websites that are controlled by a single individual or organization and used primarily to build backlinks to a “money site” in order to influence its ranking in search engines such as Google. The core idea behind a PBN is based on the importance of backlinks in Google’s ranking algorithm. Since Google views backlinks as signals of authority and trust, some website owners attempt to artificially create these signals through a controlled network of sites.
In a typical PBN setup, the owner acquires expired or aged domains that already have existing authority, backlinks, and history. These domains are rebuilt with new content and hosted separately, often using different IP addresses, hosting providers, themes, and ownership details to make them appear unrelated. Within the content published on these sites, links are strategically placed that point to the main website the owner wants to rank higher. By doing this, the owner attempts to pass link equity (also known as “link juice”) from the PBN sites to the target website.
The purpose of a PBN is to give the impression that the target website is naturally earning links from multiple independent sources. If done effectively, this can temporarily improve keyword rankings, increase organic visibility, and drive more traffic from search results.
Streaming Film
Nonton Film gratis
Jasa Backlink
Download Anime Batch